If you are checking the PM Mudra Loan age limit 2026, the practical starting point is 18 years. Government training material on MUDRA loans states that the person taking the loan should be at least 18, while the current Department of Financial Services (DFS) PMMY page does not publish a universal maximum applicant age. That means an older applicant should not assume that a fixed upper age such as 60 or 65 applies across every lender; the lending institution can apply its own credit, repayment and documentation conditions.
Use the table below as a quick reference, then read the lender-specific points carefully. PMMY is a loan programme, so age eligibility and credit approval are separate questions.
PM Mudra Loan Age Limit 2026 at a Glance
| Rule | 2026 position |
|---|---|
| Minimum age | 18 years |
| Universal maximum age | No single maximum age is stated on the current DFS PMMY overview |
| Age calculation | Applicant must satisfy the lender’s eligibility and documentation requirements on the application date |
| Scheme | Pradhan Mantri MUDRA Yojana (PMMY) |
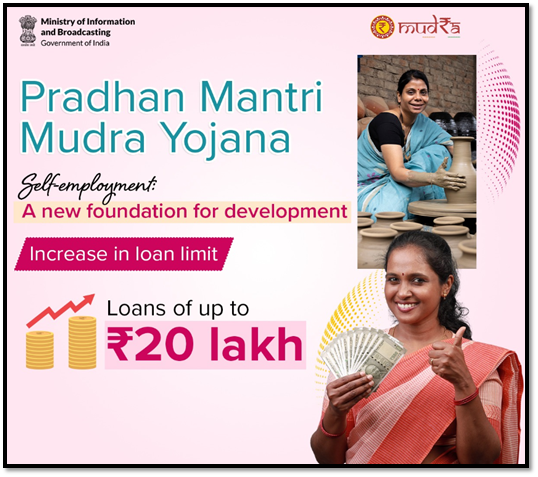
| Loan ceiling | Up to ₹20 lakh under Tarun Plus for eligible repeat Tarun borrowers |
| Collateral | Collateral is not required under the PMMY scheme framework |
What Is the Minimum Age for a Mudra Loan?
The commonly stated minimum age for a PMMY borrower is 18 years. A Government of India entrepreneurship-learning module says that the minimum age of the person taking a MUDRA loan should be 18 years. This is consistent with the way PMMY is structured around individual entrepreneurs and small business activity.
For a person who has just turned 18, the important point is that reaching the minimum age does not automatically guarantee a loan. PMMY is a credit scheme, not an age-based cash benefit. The applicant still needs a viable income-generating business proposal, acceptable KYC and business documents, and must satisfy the lending institution’s credit assessment.
Is There a Maximum Age Limit for PM Mudra Loan in 2026?
The current DFS description of PMMY does not state one universal maximum applicant age. This is an important distinction because some older online articles describe a 65-year maximum. Such figures can reflect an individual lender’s policy or older informational material rather than a scheme-wide upper-age rule.
Therefore, a 60-year-old, 65-year-old or older applicant should not treat age alone as an automatic rejection under PMMY. The lender may consider repayment capacity, business cash flow, credit history, existing liabilities, proposed tenure and other underwriting factors. The final lending decision remains with the participating bank, NBFC or microfinance institution.
Why Do Some Websites Say the Mudra Age Limit Is 18 to 65?
The 18–65 figure appears in several older or secondary descriptions of Mudra loans. It should not automatically be treated as the current universal PMMY rule. For example, older government-linked educational material has described a maximum age, while the present DFS PMMY page focuses on the scheme’s loan categories, eligible activities, participating lending institutions and collateral-free structure rather than publishing one scheme-wide upper-age cutoff.
For 2026, the safer way to read the rule is: 18 is the established minimum in government educational material, but there is no single maximum age stated on the current central PMMY overview. If a lender asks for a maximum age, follow that lender’s current policy for the specific product and repayment period.
How Is Age Calculated for a Mudra Loan?
Age is normally established from the identity and date-of-birth documents submitted during KYC and loan processing. Applicants should keep their name and date of birth consistent across Aadhaar, PAN, bank records and other documents where applicable.
- Turning 18: If your date of birth means you have completed 18 years, you can meet the basic age threshold.
- DOB proof: Use the date-of-birth information accepted by the lender during KYC.
- Older applicants: Do not rely on an internet article claiming an automatic 65-year cutoff; check the participating lender’s current policy.
- Repayment period: Even without a scheme-wide maximum age, a lender may assess whether the proposed repayment period is appropriate for the applicant’s age and financial position.
PMMY Loan Categories in 2026
PMMY currently has four loan categories. The categories reflect the size and stage of the business requirement rather than separate age bands.
| Category | Loan amount | Important condition |
|---|---|---|
| Shishu | Up to ₹50,000 | Designed for very small business requirements |
| Kishore | Above ₹50,000 to ₹5 lakh | For a higher level of business funding |
| Tarun | Above ₹5 lakh to ₹10 lakh | For larger eligible business requirements |
| Tarun Plus | Above ₹10 lakh to ₹20 lakh | For entrepreneurs who have successfully repaid a previous Tarun loan |
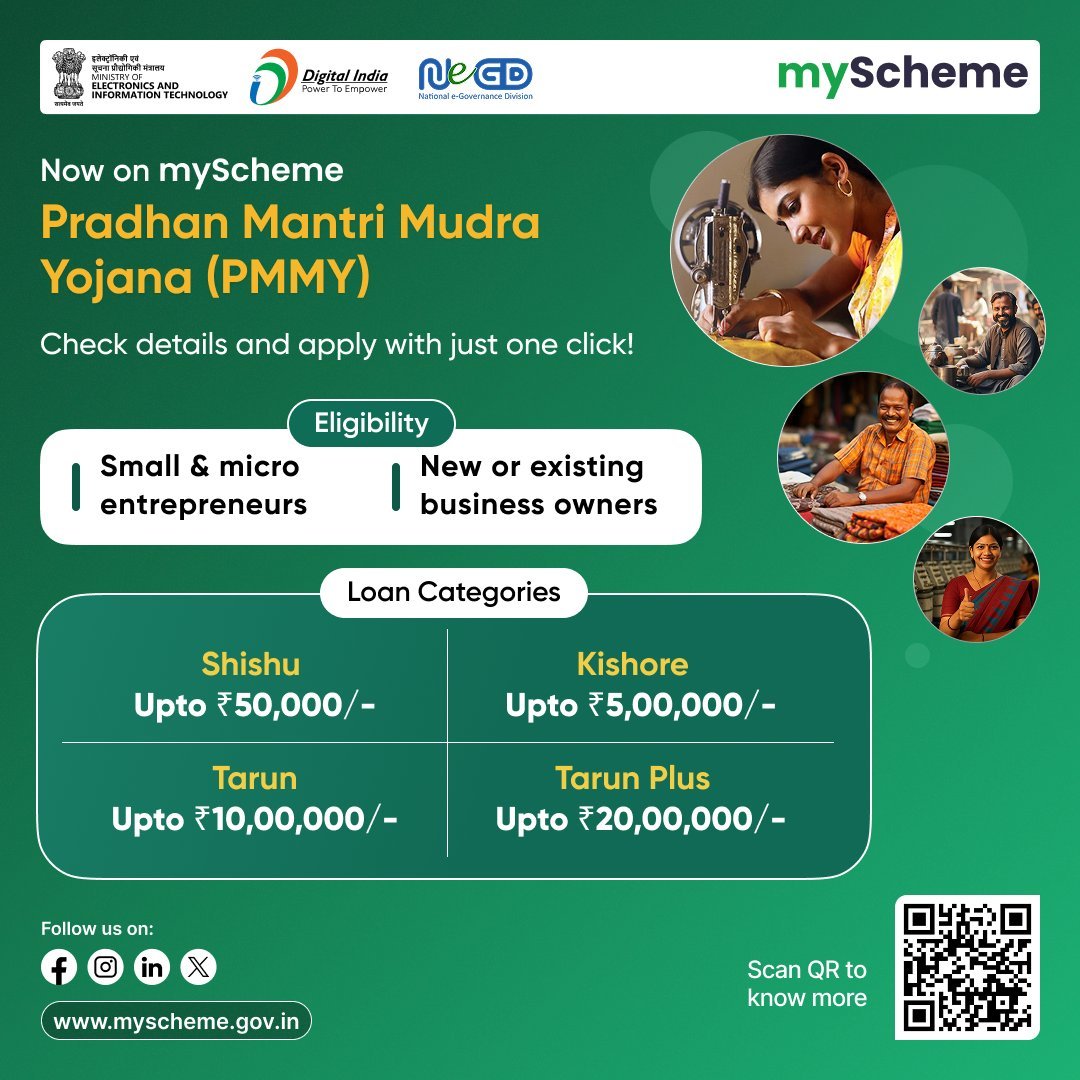
What Is Tarun Plus and Does Age Affect It?
Tarun Plus was introduced for borrowers who have availed and successfully repaid a previous Tarun-category MUDRA loan. It permits eligible repeat borrowers to seek loans above ₹10 lakh and up to ₹20 lakh. The category is therefore linked to previous repayment history, not to a special age bracket.
For an older entrepreneur, this means that age is only one part of the lending assessment. A lender can examine the earlier loan record, current business position and repayment capacity before deciding whether to sanction a new loan.
Who Can Get a PM Mudra Loan?
PMMY is intended to provide institutional, collateral-free credit to micro enterprises and small business activities. Current government information describes eligible activities across manufacturing, trading and services, including allied agricultural activities such as poultry, dairy and beekeeping.
- Individuals with an eligible income-generating business proposal.
- Micro and small business operators requiring term finance or working capital.
- Entrepreneurs in manufacturing, trading and services.
- Businesses involved in specified agriculture-allied activities.
- Eligible new or existing enterprises, subject to the lender’s assessment.
PMMY is different from a subsidy scheme where the government simply pays an applicant after an age test. The loan is sanctioned through participating lending institutions, and the applicant must meet the institution’s credit and documentation requirements.
Documents Commonly Needed for a Mudra Loan
Exact documentation varies by lender, loan size, business structure and applicant profile. Commonly requested documents can include identity and address proof, PAN where applicable, photographs, bank statements, business information and evidence supporting the proposed activity.
- Aadhaar or another accepted identity document.
- PAN, where required.
- Address proof and photographs.
- Bank account details and relevant statements.
- Business or enterprise documents, where applicable.
- Information supporting the business plan, estimated income and expenditure.
- Additional documents requested by the participating lender.
Does PMMY Require Collateral?
One of PMMY’s central features is access to collateral-free institutional credit. The DFS describes PMMY loans as collateral-free. However, collateral-free does not mean automatic approval or that every other lending condition disappears. The lender can still evaluate the applicant’s creditworthiness, business plan, repayment ability and required documentation.
Can a New Entrepreneur Apply for a Mudra Loan?
Yes. Government information on PMMY identifies the scheme with micro and small entrepreneurs and reports substantial participation by new entrepreneurs. A first-time entrepreneur can therefore explore PMMY if the proposed activity is eligible and the applicant satisfies the lending institution’s requirements.
Being 18 or older is only the starting point. A strong application should clearly explain what the business will sell, how much funding is needed, expected revenue, operating costs, repayment capacity and the purpose of the loan.
PM Mudra Loan Age Limit Examples
| Applicant | Age position | What it means |
|---|---|---|
| 17 years 11 months | Below 18 | Does not meet the stated minimum age |
| 18 years | Minimum threshold reached | Can meet the basic age requirement, subject to lending rules |
| 30 years | Above minimum | Age itself is not a barrier |
| 60 years | Older applicant | No universal maximum is stated on the current DFS PMMY overview; lender policy still matters |
| 65+ years | Older applicant | Do not assume an automatic scheme-wide rejection; confirm the lender’s current underwriting and repayment rules |
PMMY vs PMEGP: Do Not Mix the Age Rules
PMMY and the Prime Minister’s Employment Generation Programme are both associated with entrepreneurship, but they are different programmes. PMEGP has an explicit current eligibility rule that an applicant must be above 18. PMMY is a collateral-free credit framework delivered through participating lending institutions, with its own product categories and underwriting.
If you are comparing the two, read the age rule together with the purpose of the finance, project cost, education requirements, subsidy structure and other eligibility conditions. See our PMEGP age-limit guide for the separate PMEGP rules.
PMMY and PM Vishwakarma Are Also Different
Traditional artisans may also encounter PM Vishwakarma, but its eligibility framework is different. PM Vishwakarma requires a minimum age of 18 on the registration date and applies trade, family, occupation and previous-loan conditions. Do not use the PM Vishwakarma age rule as a substitute for the PMMY lending rules.
You can read the site’s PM Vishwakarma age-limit guide separately.
How to Apply for a Mudra Loan in 2026
- Identify the business activity and funding requirement.
- Choose the appropriate PMMY category: Shishu, Kishore, Tarun or, where applicable, Tarun Plus.
- Prepare KYC and business documents.
- Prepare a clear business plan or explanation of the proposed income-generating activity.
- Approach an eligible Member Lending Institution such as a participating bank, NBFC or MFI.
- Submit the application and supporting documents.
- Respond to lender verification and credit-assessment requests.
- Review the sanction terms, repayment schedule and applicable charges before accepting the facility.
Government information also points applicants toward digital credit journeys such as JanSamarth for specified credit-linked schemes. Availability and the exact application route can vary by lender and product.
PMMY Age Limit 2026: Important Mistakes to Avoid
- Do not confuse 18+ with guaranteed approval. Age only establishes one eligibility element.
- Do not assume 65 is a universal PMMY ceiling. Check the current lender’s policy.
- Do not describe Tarun Plus as a general ₹20 lakh loan. It is linked to successful repayment of a previous Tarun loan.
- Do not treat collateral-free as interest-free. A PMMY loan remains a credit facility with repayment obligations.
- Do not submit inconsistent DOB details. KYC records should match the documents requested by the lender.
- Do not pay unofficial agents for guaranteed approval. Use the participating institution or official government channels.
PMMY in 2026: What Has Changed?
The biggest recent change is the expansion of the maximum PMMY loan framework from ₹10 lakh to ₹20 lakh through the introduction of Tarun Plus for qualifying repeat Tarun borrowers. In April 2026, the Government reported that PMMY had crossed 57 crore loans and ₹40.07 lakh crore in cumulative disbursements as of 27 March 2026. The scheme continues to cover non-corporate, non-farm income-generating activities across manufacturing, trading, services and allied agriculture.
The current framework therefore combines a long-running small-business credit programme with four loan stages. The age question remains comparatively simple: 18 is the stated minimum in government learning material, while the current central PMMY overview does not prescribe one universal upper age.
Frequently Asked Questions
Is the Mudra loan minimum age 18?
Yes. Government of India educational material for MUDRA loans states that the person taking the loan should be at least 18 years old.
Is the Mudra loan maximum age 65?
There is no single maximum age stated on the current DFS PMMY overview. Some older or secondary sources mention 65, but applicants should verify the current participating lender’s policy rather than treating 65 as a universal scheme rule.
Can a 60-year-old apply for a Mudra loan?
Age 60 is not itself identified as a universal PMMY disqualification on the current central scheme overview. The applicant should approach a participating lender and confirm its current credit and repayment criteria.
What is the maximum Mudra loan in 2026?
The PMMY framework allows loans up to ₹20 lakh under Tarun Plus for entrepreneurs who have successfully repaid a previous Tarun-category loan. Shishu, Kishore and Tarun have lower ceilings.
Can a new business get a Mudra loan?
Eligible new entrepreneurs can seek PMMY credit, subject to the lender’s assessment. The applicant needs an eligible income-generating activity and must satisfy the institution’s documentation and credit requirements.
Is Mudra loan collateral-free?
Yes, PMMY is designed to provide collateral-free institutional credit. However, collateral-free does not mean automatic approval or exemption from normal lender checks.
Age, Tenure and Repayment Capacity
For older applicants, the absence of a universal scheme-wide maximum age does not remove the importance of repayment tenure. A lender may assess whether the proposed loan period is compatible with the applicant’s expected income, business cash flow and overall repayment capacity. Two applicants of the same age can therefore receive different decisions because their businesses, financial histories and loan requirements are different.
Similarly, a younger applicant who satisfies the 18-year minimum still has to demonstrate a credible business purpose. The PMMY age rule should therefore be understood as a threshold, not as a promise that a loan will be sanctioned once the threshold is crossed.
How to Check Your DOB Before Applying
Before submitting an application, check that the date of birth in the documents you intend to use is consistent. If your Aadhaar, PAN, bank records or another accepted document contains a different date, resolve the discrepancy or ask the lender which document it will accept for KYC. This is particularly important for applicants who are close to the 18-year threshold.
A simple self-check is to calculate your completed age on the application date rather than simply subtracting birth years. For example, someone born on 20 September 2008 reaches 18 on 20 September 2026. Before that date, the person has not completed 18 years.
What the 2026 PMMY Data Shows
PMMY remains a large-scale credit programme. A PIB backgrounder published in April 2026 reported more than 57 crore loans and ₹40.07 lakh crore in cumulative disbursements as of 27 March 2026. It also reported that more than 12 crore accounts belonged to new entrepreneurs. These figures describe the scale of the programme; they do not change the individual lender’s assessment of a new application.
Before You Apply: Quick Checklist
- Confirm that you have completed 18 years.
- Check your DOB and KYC documents for consistency.
- Identify the exact business activity and its PMMY eligibility.
- Estimate the amount actually required instead of automatically seeking the maximum.
- Choose the appropriate PMMY category.
- Prepare a realistic repayment plan based on business cash flow.
- Use an official participating lender or recognised government application channel.
- Read the sanction letter and repayment terms before accepting the loan.
Why Lender Policy Still Matters
PMMY provides the overall scheme framework, but the actual loan is processed by a participating lending institution. That institution may have additional documentation, credit-score, business-vintage, repayment-tenure or internal risk requirements. These conditions should be checked directly before application, especially when the applicant is near an age threshold or is seeking a longer repayment period.
In other words, the question “Am I old enough?” is only the first screening question. The more complete question is whether the applicant, proposed enterprise and requested loan satisfy both the PMMY framework and the lender’s current underwriting requirements.
Final Takeaway
For PM Mudra Loan age limit 2026, use 18 years as the basic minimum age. The current central PMMY information does not state a universal maximum applicant age, so an applicant should not automatically apply a 65-year ceiling to every Mudra loan. Instead, check the participating lender’s current underwriting rules, repayment conditions and documentation requirements.
PMMY is a credit programme for eligible income-generating micro and small business activities. Age is only one part of the application: the business purpose, loan category, repayment capacity, KYC and lender assessment also matter.